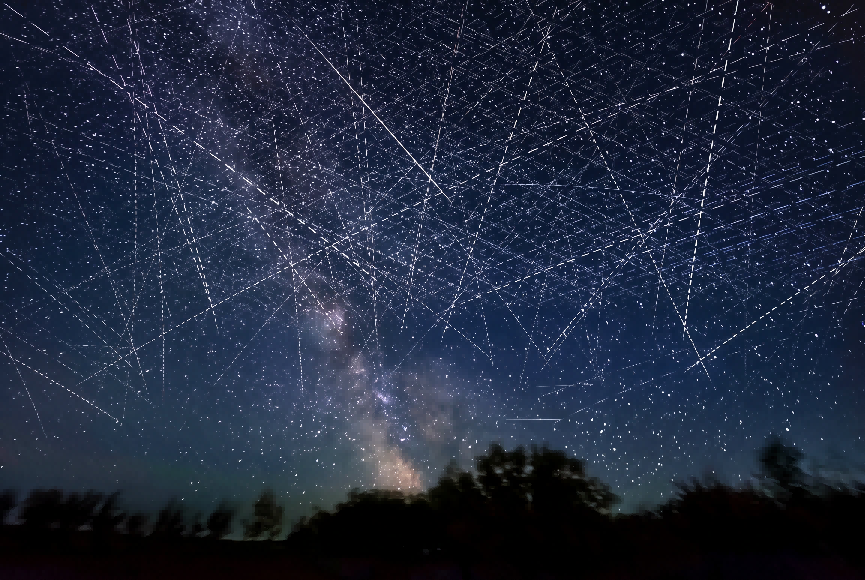
Broadband reaches a home by two routes. One runs through buried or aerial cables, and the other comes from a satellite constellation flying overhead. Fiber is built outward and works best where numerous users share the same infrastructure. LEO can serve scattered homes, ships, aircraft, and emergency sites without extending any terrestrial line to the end user. On LEO tracking maps, the space orbit is already crowded with Starlink and Amazon Leo satellites. Sometime in the future, we may see series of satellite-based wireless plans juxtapose with traditional mobile plans.
Telecom providers and ISPs have every reason to worry. The U.S restructured the BEAD toward a technology-neutral approach, allowing LEO providers to compete for eligible projects. LEO broadband has already become a globally scalable business model. By March 2026, Starlink was operating 9600 satellites and serving 10.3 million users globally. It brings value where terrestrial infrastructure is absent or the population is vastly dispersed. Nevertheless, the two systems organize their costs differently: The major costs for fiber have been measured in decades of operation, whereas the long-term cost LEO broadband is yet to be fully perceived – leaving it far from replacing the mature fiber broadband across the market.
THE COST HAS SHIFTED
For LEO broadband to become a mass-market service, the phased-array antenna had to become inexpensive enough to manufacture at scale. Although SpaceX had reduced the manufacturing cost of a Starlink kit by 59% from its 2022 level, it still records kit production, customer support and installation among the operating costs of its connectivity business. These expenses may appear in an upfront hardware price, a monthly fee, a promotion or the ongoing cost of servicing the subscriber, so the price of the dish alone does not reveal the full cost of acquiring and maintaining a connection. The problem has become a broader task of managing equipment, customers and revenue over the life of the service.
The terminal, of course, is only the edge of a much larger network. Each connection depends on a moving constellation, repeated launches, high-capacity gateways, network operations and links into the terrestrial internet. SpaceX estimates a five-year useful life for its broadband satellites, and it may retire them earlier to manage degradation risks or introduce a newer generation; launch expenditures are capitalized as part of the satellite asset and then flow through depreciation. Adding subscribers also requires capacity in the right place, which can mean launching more satellites and expanding the ground infrastructure that supports them—costs that SpaceX records as part of its connectivity business. Even Starlink’s Community Gateway model ultimately hands traffic to local providers for distribution over last-mile fiber, fixed wireless or mobile networks. LEO therefore avoids some of the expense of building a physical line to each remote premise, but replaces it with an operating cycle of launches, satellite renewal, capacity planning and terrestrial interconnection.
THE SKY IS NOT FREE
A global satellite network operates above national borders, but it does not operate outside public rules. Before an NGSO system can use particular frequencies, its notifying administration must submit technical information to the ITU and, where required, complete coordination with other satellite networks and terrestrial services. The process covers frequency overlap, transmission power, orbital parameters and the risk of harmful interference, followed by notification and recording in the Master International Frequency Register. Large constellations must also meet staged deployment requirements intended to ensure that registered spectrum reflects satellites actually placed in service rather than capacity reserved on paper. As more systems enter similar frequency bands, engineering studies, regulatory filings and operator-to-operator coordination become continuing parts of network expansion. The cost of a constellation therefore includes not only the hardware sent into orbit, but also the institutional work required to share the sky.
International registration, in turn, does not grant automatic access to every national market. A provider must still obtain the licenses required by each country for user terminals, frequency use and commercial service; in some markets, it may also need landing rights, a locally incorporated representative or a partnership with a domestic operator. Market access can consequently change with national security policy, diplomatic relations and local telecommunications rules, even where satellites already provide technical coverage overhead. These requirements matter more as new constellations enter the market with newer spacecraft, terminal designs and commercial partnerships. Amazon, for example, designed its standard consumer terminal for a manufacturing cost below $400, making low-cost customer equipment a starting assumption rather than a later engineering milestone. Established operators retain the advantages of deployed capacity, subscribers and operating experience, while later entrants can build on more recent technology and lessons already demonstrated in the market. The resulting competition will be shaped as much by spectrum coordination and national authorization as by the number of satellites each company can launch.
IT’S GOOD TO BE BORING
Fiber faces a more familiar set of constraints. Extending a network still requires route design, permits, rights of way, poles or trenches, construction crews, distribution equipment and individual drops to customer premises. These costs can be high, particularly where homes are widely dispersed or underground construction must pass through difficult terrain. In the United States, the Fiber Broadband Association and Cartesian reported median 2025 deployment costs of $18 per foot for underground fiber and $8 per foot for aerial construction, with substantial variation by region, terrain and construction method. Labor accounted for 72% of underground deployment costs and 64% of aerial costs, making it the largest component in both cases. None of this makes fiber automatically inexpensive; it makes its expense comparatively visible. Operators can identify where the money goes, compare construction methods and adjust routes, contractors, project schedules and installation practices before the network is built.
That visibility also gives the fiber supply chain a clear direction for improvement. Because so much of the cost sits in field labor, manufacturers can create value by reducing the number of measurements, enclosure openings, splices, tests and return visits required at each location. Factory-tested, pre-connectorized cables and modular terminals move part of this work from unpredictable field conditions into a controlled production environment, allowing technicians to make connections in minutes rather than preparing and splicing every fiber on site.
This is where the fiber supply chain still has room to innovate. CQT works along this part of the cost curve, supplying passive ODN and FTTH components designed to simplify distribution, termination and customer connection across the access network. The commercial value of such products does not rest on the novelty of an individual connector or enclosure; it appears in shorter installation times, fewer specialized tools, more consistent workmanship and easier replacement when something fails. In a mature infrastructure industry, innovation often means removing one more field operation from a process that operators already understand.
This leaves LEO and fiber with different, but increasingly connected, roles. LEO expands the places where broadband can be delivered economically, especially when users are remote, mobile, temporarily located or in need of rapid service. Its next stage of development will depend on managing terminal turnover, satellite replacement, regional capacity, spectrum coordination and market access at greater scale. Fiber will remain central to dense and steadily growing fixed-broadband markets, where long-lived passive infrastructure can support repeated upgrades to the electronics at either end. It will also continue to carry traffic into and out of satellite gateways, just as satellite capacity may feed local fiber, fixed-wireless and mobile access networks in places that are difficult to reach directly. LEO is therefore extending the broadband market and replacing some terrestrial links that are too slow or expensive to build, but it remains far from vanquishing fiber. The more likely future is not land or space, but space extending the network where land becomes impractical—and fiber carrying much of the traffic before and after it leaves the sky.